Adaptive Reuse Zoning Reforms That Enabled Office-to-Residential Conversions
Cities eliminated zoning rules that had made office conversions illegal or unprofitable for decades.
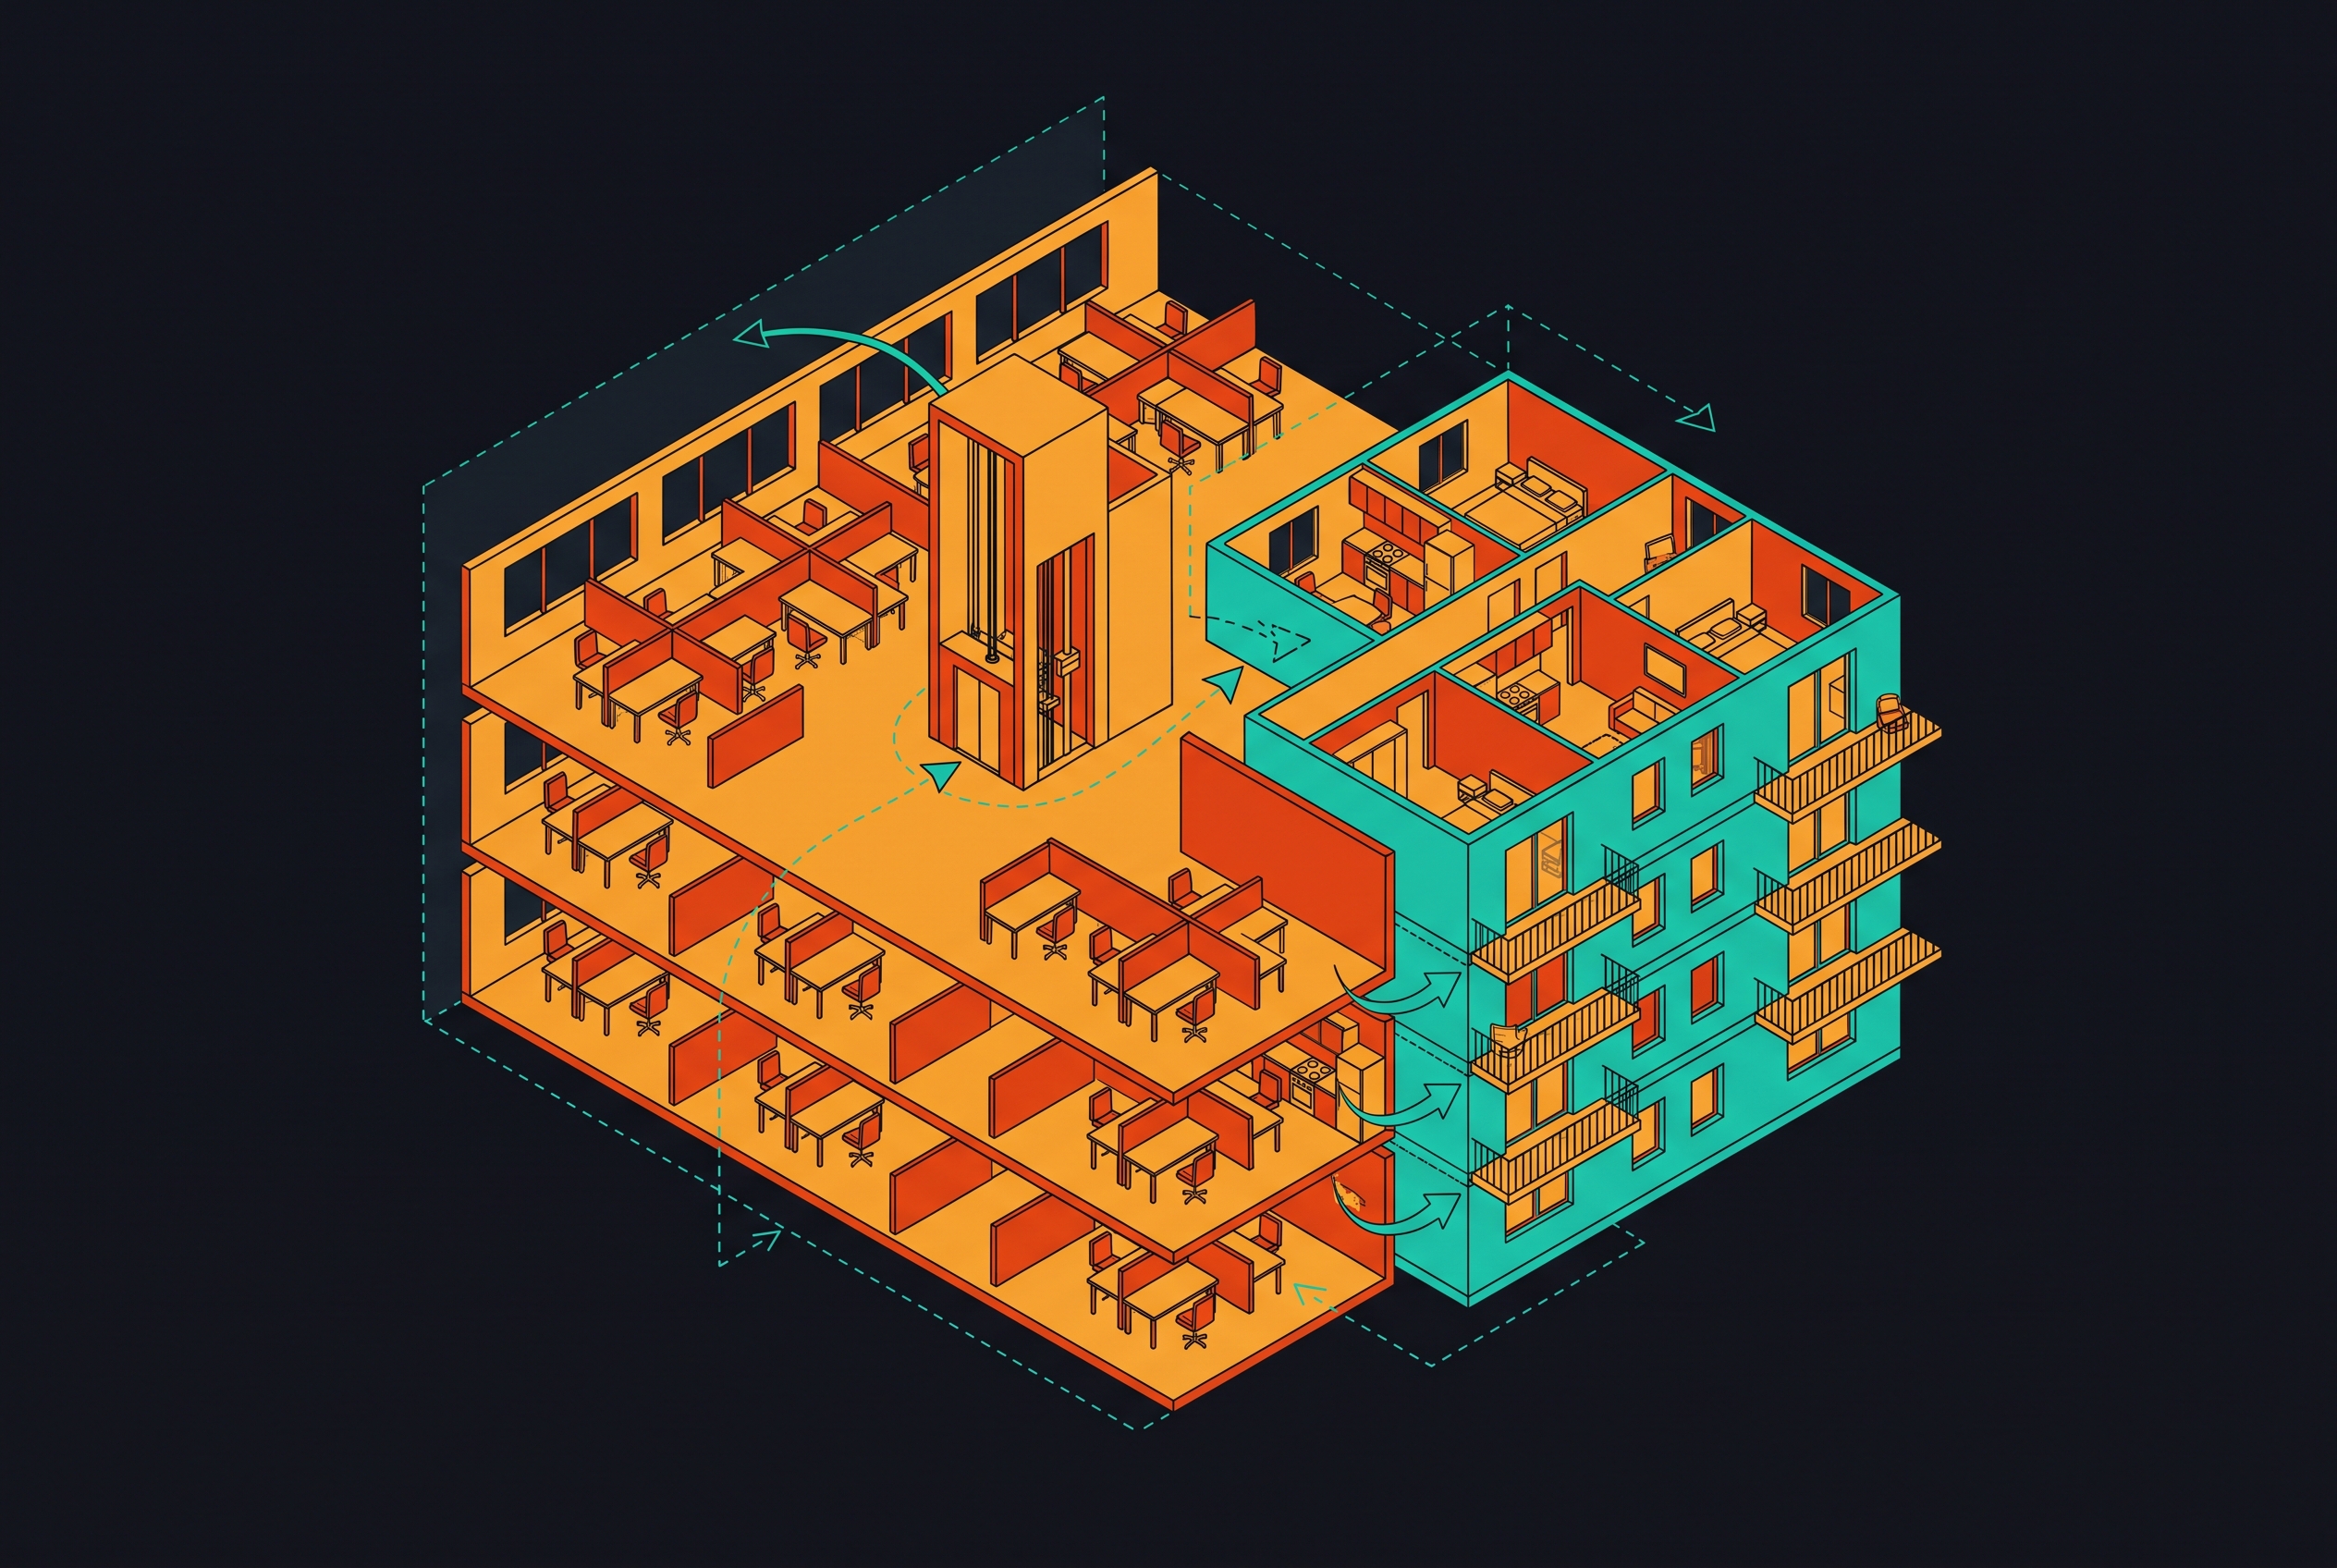
The wave of office-to-residential conversions reshaping American downtowns didn't happen on its own. Cities engineered it, by rewriting the specific zoning rules that had made conversions illegal, slow, or financially pointless for decades.
Why zoning reforms were needed to make office-to-residential conversions possible
Office buildings sat empty for years while housing got more expensive, and the two problems rarely met, because zoning codes were built to keep them apart. Most post-war American cities wrote rules that made office-to-residential conversion either against the law or a bet that lost money. The buildings weren't the obstacle. The codes were built to separate commercial and residential uses, full stop, and that separation held for decades even as the reasons behind it stopped making sense.
New York's rules show how specific the blockage got. Before reform, conversions were mostly limited to nonresidential buildings built before 1961, with narrower cutoffs of 1977 in the Financial District and 1997 in Special Mixed-Use Districts. That left out most of the commercial stock built during the city's biggest office construction booms. A building completed well after those cutoffs could sit half-empty for years and still be legally untouchable for housing.
Location made it worse. Conversions were allowed only in certain neighborhoods, so even a building old enough to qualify could still need a variance or a full rezoning if it sat on the wrong block. Single-use zoning, density limits, and parking minimums piled on top of that. MRSC's April 2025 analysis identifies these rules as the kind that keep discouraging conversions in many places that haven't reformed yet. None of this was about whether a building could physically become an apartment. It was about whether the rulebook would let it try.
How converging vacancy and housing crises created political will for reform
Two crises that usually get fought over separately ended up pointing at the same fix. Office vacancy hit record highs at the same time housing costs became politically unbearable, and that collision handed reformers something rare: a single policy tool that addressed both problems at once, which made it far easier to build a coalition than in a typical zoning fight.
The overlap wasn't an accident of geography, either. The empty buildings and the convertible buildings were often the exact same addresses.
Montgomery County's April 2025 legislation spelled out the money side of the argument. The Urban Land Institute added a scale argument cities could point to: adaptive reuse, in its framing, could account for a meaningful share of new housing in cities, a point MRSC's analysis cites directly.
None of this played out evenly. Cities with the worst vacancy and the sharpest housing price spikes moved first and hardest. Cities still had to decide which specific levers to pull, and in what order.
How cities redrew eligibility boundaries for conversions
The first lever, and the one everything else depends on, is eligibility. Before any building can get a fast review or a tax break, it has to qualify for conversion in the first place, and that meant changing the cutoff dates and the maps that had locked most of the office stock out for decades.
New York made its biggest move through City of Yes, which the City Council adopted on December 5, 2024. It pushed the eligibility cutoff from 1961 to December 31, 1990, and opened the qualifying geography to nearly the whole city. That single change brought decades of office construction back into play. Lifting the cap fixed that.
Montgomery County took a different approach: it built a brand-new use category instead of a date cutoff. ZTA 25-03 created "Commercial to Residential Reconstruction," defined as any building at least half vacant, mostly office space, and taller than two stories. That category applies across Commercial/Residential Zones, Neighborhood Residential Zones, and Employment Office Zones, so in practice the entire county is eligible.
What these reforms share is a shift in the question developers have to ask. Before reform, the central question was whether a building was legally allowed to convert. After reform, in the cities that moved, the question becomes whether a project pencils out physically and financially, a question the market is actually equipped to answer.
Cutting approval time: the expedited-review reforms that changed project economics
Eligibility gets a project to the starting line. Approval time decides whether it ever leaves it. Every month a project spends waiting on permits is a month of carrying costs, interest payments, and holding risk, and for a project with thin margins, that delay alone can turn a workable deal into a dead one. Cities treated the review clock as a cost problem, not a paperwork problem.
Boston's Office to Residential Conversion Program cut a standard 18-month Article 80 review down to roughly six months. Montgomery County built its own fast lane into ZTA 25-03, which created an expedited track for the new Commercial to Residential Reconstruction category. That track wasn't invented from scratch. It borrowed its structure from expedited pathways the county had already set up for other priority projects, including Signature Business Headquarters, Biohealth Priority Campuses, and Mixed-Income Housing Communities.
New York took a different angle on the same problem. Its Office Conversion Accelerator Program, launched in 2023, did more than speed up any single review step. It gave developers one point of contact across city agencies, closing the gap where inter-agency handoffs used to stretch timelines in unpredictable ways.
The pattern holds across all three cities: expedited review appears paired with eligibility reform, not standing alone. And faster approval doesn't just save time. It removes a layer of uncertainty that developers have to price into every underwriting model, which makes marginal projects easier to finance in underwriting before a single incentive dollar is applied.
Financial incentives cities used to close the conversion gap when eligibility and speed were not enough
Legal eligibility and a fast permit stamp can still leave a lot of projects underwater. The cost of converting an office building often outruns the value of the apartments that come out of it, and the Bipartisan Policy Center's analysis of New York treats that gap as a built-in feature of conversion economics, not a rare exception. Closing it took direct financial intervention.
Property tax abatement became the workhorse tool. Montgomery County's Bill 2-25 set up a 20-year PILOT for projects that include at least 17.5% affordable housing.
New York added its own tool in 2024: the city's conversion overview describes the 467-m tax incentive as offering up to 35 years of tax relief for conversions that build in affordable units.
States started stacking incentives on top of city programs alongside local governments. The Commonwealth's Affordable Housing Trust also put direct grant money behind larger projects above 70,000 square feet. Seattle's Council Bill 120937 defers the city's sales-and-use tax for qualifying conversions, and developers can stack that deferral with the city's existing multifamily property-tax exemption.
These programs carry a real fiscal trade-off in actual money, not an abstraction. Montgomery County's own legislative record shows pushback against the 20-year PILOT over the near-term tax revenue it gives up, and that pushback came from inside the government that backed the bill. Every city that weighs a similar program will run into the same argument.
Reform combinations behind the cities that converted earliest
Look at which cities actually produced units: a pattern jumps out fast, since no single reform did the work alone. The cities with real pipelines stacked eligibility expansion, faster approval, and financial incentives together, in a deliberate sequence, rather than betting on one tool to carry the whole load.
New York leads the national pipeline in units actively under construction. That didn't come from the 467-m tax credit alone or City of Yes alone. It came from layering City of Yes eligibility expansion, the Office Conversion Accelerator Program's streamlined coordination, and the 467-m incentive into one sequence, as both NYC's 2025 conversion overview and Gensler's May 2026 analysis reflect.
Boston's numbers back up the same point. Five projects totaling 306 units are already under construction, and 281 Franklin Street is now fully tenanted.
Dallas offers the counterexample. The completed first phase of Santander Tower, now Peridot Residences, delivered 291 units, but it got there through a project-specific financial structure built for that one deal, not a citywide program. That's a useful proof that one-off conversions are possible without a reform package. It's also proof that one-off deals don't scale the way a programmatic approach does.
Design matters too, but it plays a supporting role, not the lead. Gensler's work on New York projects, including Pearl House, shows techniques like blind shafts cut through the building core, selective demolition to let in light, and stacking amenities vertically to free up perimeter units for living space. And timing matters as much as the toolkit itself. In several early programs, eligibility reform without financing tools attracted plenty of applications but very few construction starts, because applying costs nothing and building costs everything.
The physical, fiscal, and affordability limits of zoning-led conversion strategies
Zoning reform opens the door. It doesn't make every building walk through it. A meaningful share of the national office stock can't convert no matter how the rules change, because the physical layout or the underlying economics won't support it.
MRSC's April 2025 analysis finds that roughly a quarter of office buildings nationally are likely candidates for conversion. In the Puget Sound region, the share is even smaller, because the office inventory there skews newer and wasn't built with the layouts that make conversion easiest.
The floor plate is often the deciding factor. Getting natural light into the interior units in buildings like that requires serious structural work, and that work eats into usable square footage, which shrinks the revenue side of the entire project.
Affordability rules add another layer of strain, even when the intent behind them is sound. California's labor requirements attached to zoning concessions have stopped otherwise-eligible projects in a similar way.
Conversions, even at their most successful, won't close the national housing gap by themselves. The Bipartisan Policy Center's analysis, cited in its NYC explainer, concludes that conversions can supply only a modest share of total housing need measured against the scale of the shortage nationally. That's not a reason to abandon the approach. It's a reason to size expectations correctly.
Emerging adaptations that are extending the model to harder cases
The limits above aren't fixed. Cities, designers, and lenders are actively working around each one, and the feasible pool of convertible buildings is growing as a result, not shrinking.
Building age is shifting first. These buildings came with better infrastructure than their mid-century predecessors, which lowers the cost of retrofitting them for residential use.
Design is addressing the floor-plate layout directly through unit configuration. A 2024 study from Pew Charitable Trusts and Gensler points to dormitory-style layouts, small units ringing the perimeter of each floor with shared amenities in the center, as a way to cut construction costs significantly compared to conventional apartment layouts. Selective demolition tackles the same problem from a different angle: removing structural bays, carving lightwells, or opening voids through the floor plate can bring in daylight and add unit count to buildings once considered marginal, a technique Gensler's May 2026 piece documents across several completed projects.
Financing is adapting as well. The C-PACE structure used on the Post Brothers project in D.C. shows that institutional capital can reach conversion projects that traditional bank lending won't touch, reducing how much of the financing gap has to be closed by public subsidy alone.
Even geography is starting to shift. Suburban office campuses, largely left out of the current reform wave, could add housing supply equivalent to a meaningful share of a decade's worth of production in constrained markets. So the next round of reform will need to stretch eligibility and incentive frameworks past downtown cores. The framework works only as long as cities keep updating it to match the stock actually available to convert.
A working framework for policymakers and developers from the reform record
Line up the cases, New York, Boston, Montgomery County, Washington D.C., and the Washington state examples, and a consistent three-layer structure emerges: eligibility expansion defines which buildings are even in play, expedited approval cuts the timeline risk, and targeted financial incentives close the remaining value gap. The sequence carries as much weight as the individual tools themselves.
Eligibility comes first, and skipping it undercuts everything else. Faster approval and generous incentives mean little if they apply to a tiny sliver of buildings, which is what New York's pre-2024 rules demonstrated for years.
The strongest fiscal argument for an incentive program starts from the baseline of a declining asset. Montgomery County's legislative record lays out a version of this argument other jurisdictions can reuse directly: a vacant office building is already losing assessed value and shedding tax revenue, so a PILOT that captures future residential value still nets out ahead, even after accounting for the years of abatement.
Deadlines turn a policy on paper into units on the ground. Boston's structure, applications due by December 31, 2026, construction required to start by December 31, 2027, creates real urgency without closing off the option permanently.
Affordability requirements need to match the actual math of a conversion project, not get copied wholesale from ground-up development rules. The programs that have generated the most construction activity set affordability minimums that mean something, while still leaving enough margin for the deal to function.
Developers reading the market should treat a stacked reform package, not any single incentive in isolation, as the real signal that a city is ready for conversion activity. The underwriting should follow the specific eligibility rules, approval timelines, and financial terms of each program on its own terms, rather than assuming one city's toolkit transfers directly to another.
Sources
- Office-to-Residential Conversions in New York City
Provided the Bipartisan Policy Center's analysis that conversions can supply only a modest share of total housing need, cited in the section on limits of conversion strategies.
- MRSC - Office-to-Housing Conversion Adds Vibrancy to Downtowns
Supplied the April 2025 analysis identifying zoning rules that discourage conversions, the estimate that roughly a quarter of office buildings nationally are conversion candidates, and details on Seattle's Council Bill 120937.
- Council Approves Legislation to Speed Up and Reduce Costs for Office-to-Housing Conversions
Provided details on Montgomery County's ZTA 25-03 and Bill 2-25, including the new Commercial to Residential Reconstruction category, expedited review track, and 20-year PILOT structure.
- Extension of Boston’s Office to Residential Conversion Program Presents Unique Opportunity for Developers
Provided details on Boston's Office to Residential Conversion Program, including the shortened six-month review, application and construction deadlines, grant thresholds, and the five projects totaling 306 units under construction.
- NYC Office-to-Residential Conversions 2025
Supplied specifics on New York's pre-reform eligibility cutoff dates, the City of Yes expansion to the 1990 cutoff, and the 467-m tax incentive offering up to 35 years of tax relief.